Customer Onboarding Software for Dealers in Precious Metals and Stones (DPMS) in Singapore
Ready to Defeat Your AML Compliance Obstacles?
Citadel365 Brings Revolution with Secure Solutions to AML Compliance Problems
Customer Onboarding Software for Dealers in Precious Metals and Stones (DPMS) in Singapore: Key Takeaways
- Customer onboarding software for DPMS in Singapore helps capture and verify customer identities, screen customers, identify beneficial owners, and maintain records to support AML compliance.
- Key red flags that customer onboarding software helps detect include missing identification, repeated transactions that may indicate structuring, unverified UBOs, source-of-funds mismatches, and expired identification.
- Citadel365 supports DPMS AML compliance through identity capture, corporate verification, screening, and record management.
What Is Customer Onboarding Software for Dealers in Precious Metals and Stones (DPMS) in Singapore?
Customer onboarding software for DPMS in Singapore helps support customer due diligence (CDD) by capturing and verifying customer identity, identifying beneficial owners of corporate customers, and linking customer and transaction records to help identify transactions that may require CDD or cash transaction reporting.
Why onboarding for Dealers in Precious Metals and Stones (DPMS) in Singapore is different
DPMS dealers in Singapore are subject to specific AML/CFT requirements under the Precious Stones and Precious Metals (Prevention of Money Laundering, Terrorism Financing and Proliferation Financing) Act 2019. CDD must be performed before designated transactions, including specified cash or cash equivalent transactions exceeding SGD 20,000. Each designated transaction must also be reported to the Suspicious Transaction Reporting Office (STRO) through a Cash Transaction Report (CTR) within 15 business days, and CDD and transaction records must be kept for at least five years.
The rules also aggregate two or more sales made in a single day to the same customer, or to customers known to act on behalf of the same person, where the total cash or cash-equivalent payment exceeds SGD 20,000, and require CDD in other circumstances, such as where there is a suspicion of money laundering, terrorism financing or proliferation financing, or doubts about previously obtained customer identification information.
How Customer Onboarding Software Works: The Actual Process
Step 1: Threshold detection including linked transactions
The customer onboarding software flags cash and cash-equivalent transactions exceeding SGD 20,000 and can aggregate qualifying sales made to the same customer, or customers the dealer knows to be acting on behalf of the same person, within a single day.
This helps trigger CDD before a designated transaction and supports timely filing of Cash Transaction Reports with STRO.
Step 2: Identity capture with multi-language OCR
The software helps capture customer identification details and documents, including documents in multiple languages, using OCR and electronic verification where available.
Step 3: Source of funds for higher-risk customers
It supports the collection of source-of-funds information and supporting documents where required, for example when enhanced CDD applies to higher-risk customers or politically exposed persons (PEPs).
Step 4: Corporate customer verification
The software helps record corporate details and supports the identification of beneficial owners (UBOs).
Step 5: Screening integration
The customer onboarding software helps screen customer information against relevant sanctions lists, including targeted financial sanctions designations applicable in Singapore, and politically exposed person (PEP) lists.
Onboarding Red Flags the Software Surfaces
The key red flags that customer onboarding software helps detect:
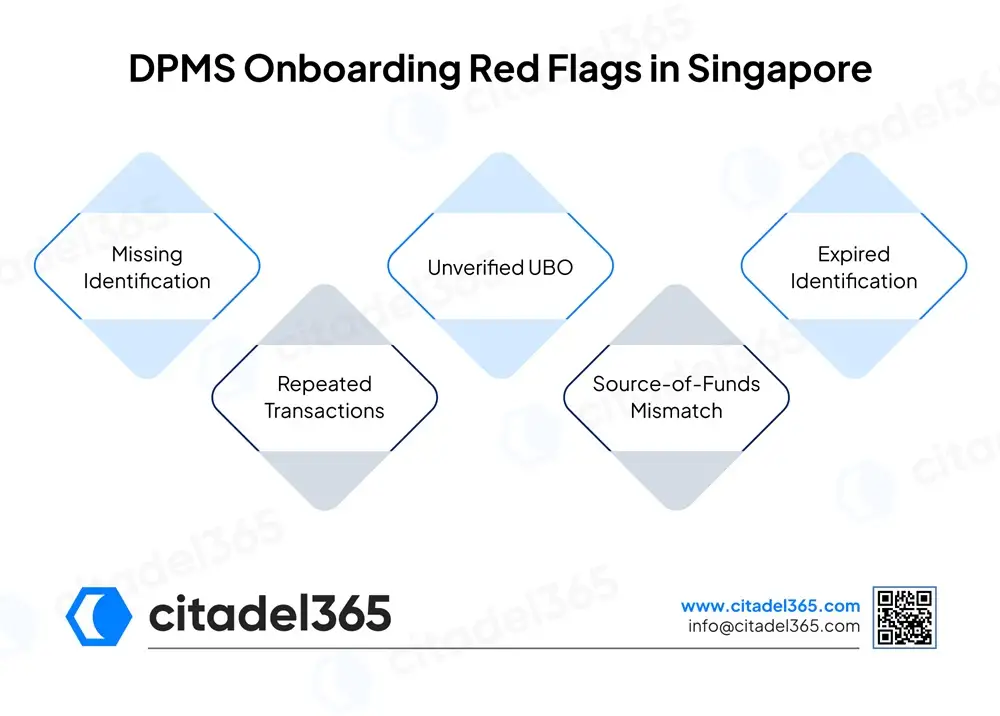
- A customer cannot provide the required identification when CDD is necessary for a transaction; the dealer must not proceed and should consider filing a suspicious transaction report (STR).
- A customer’s transactions across multiple visits show a pattern that may indicate structuring to stay below the SGD 20,000 threshold and may warrant further review or an STR.
- A corporate buyer provides ACRA registration details but does not provide required beneficial ownership information.
- A customer’s declared source of funds is inconsistent with the information or documents provided.
- A repeat customer’s identification document has expired and may require updated verification.
Manual Onboarding vs Software
Onboarding Area | Manual Process Risk | Software Advantage |
Threshold detection | Manual tracking may miss relevant transactions. | Flags relevant threshold-triggering transactions and supports same-day aggregation where applicable. |
Corporate buyer | Individual KYC only, UBO invisible | Supports corporate information capture and UBO identification. |
Supplier onboarding | No structured supplier onboarding, B2B gap | Dedicated supplier onboarding with entity capture and principal screening |
Audit trail | Paper forms, lost or incomplete at inspection | Searchable, timestamped transaction and CDD records |
How Citadel365 Supports Dealers in Precious Metals and Stones (DPMS) Onboarding in Singapore
Citadel365 helps with AML compliance for dealers in precious metals and stones in Singapore through its customer onboarding software, which enables identity data capture, corporate customer verification, screening, and transaction record management.
Citadel365 also has multilingual capabilities, supporting customer onboarding across different languages.
It also provides dedicated supplier onboarding workflows to simplify supplier information collection, verification, and record management.
Simplify DPMS Customer Onboarding in Singapore
We help strengthen your AML compliance processes with advanced customer and supplier onboarding capabilities.
Frequently Asked Questions
Customer onboarding software helps precious metals dealers capture and verify customer information, conduct screening, record corporate details, and maintain customer and transaction records to support AML compliance.
The software aggregates cash and cash-equivalent sales made in a single day to the same customer, or to customers known to act on behalf of the same person, so combined payments exceeding SGD 20,000 are treated as a designated transaction. It also links records across days to flag repeated activity that may indicate attempts to stay below the threshold.
Yes. The software helps record corporate customer details and identify ultimate beneficial owners (UBOs) to support customer due diligence.
Citadel365 supports customer identity capture, corporate verification, screening, transaction record management, multilingual capabilities, and dedicated supplier onboarding workflows, supporting overall compliance processes.
Sridhar is a Certified Anti-Money Laundering Investigator (CAMI) with over 30 years of experience in compliance, risk, and audit, including more than 20 years in AML and financial crime prevention. He has contributed to the development of UAE regulatory standards through the FERG sub-committee and has maintained active engagement with the Central Bank of the UAE on supervisory and compliance matters.